Morning Briefing — Monday 19.10: France Burns, a Make-or-Break Budget Vote and a Relief Rally
France’s worst unrest in years puts Europe’s debt question front and centre, while US indices bounce on renewed peace hopes. We preview flash PMIs, UK CPI and Tuesday’s critical French budget vote.
Morning Briefing · Monday, October 19, 2026
Bank of England governor walks out of IMF summit in protest against Russia — AOL
MORNING
Hope the weekend was enjoyed. We saw France and its cities burn over the weekend, and it looks like Europe and its economies are in trouble — indeed, the debt question is finally being queried. The bond markets have been asking that question all year!
Monday morning and indices are posting a sea of green, with both Nasdaq and Wall Street up after Friday’s sell-off. News from Trump and others that peace is still on the cards has covered a lot of the safe-haven plays from Friday.
Europe and US Previews
- ▸ECB's Panetta speaks in Manila at 05:00 GMT today — watch for any signal on the October vs. December hike debate given recent Brent strength and EUR softness.
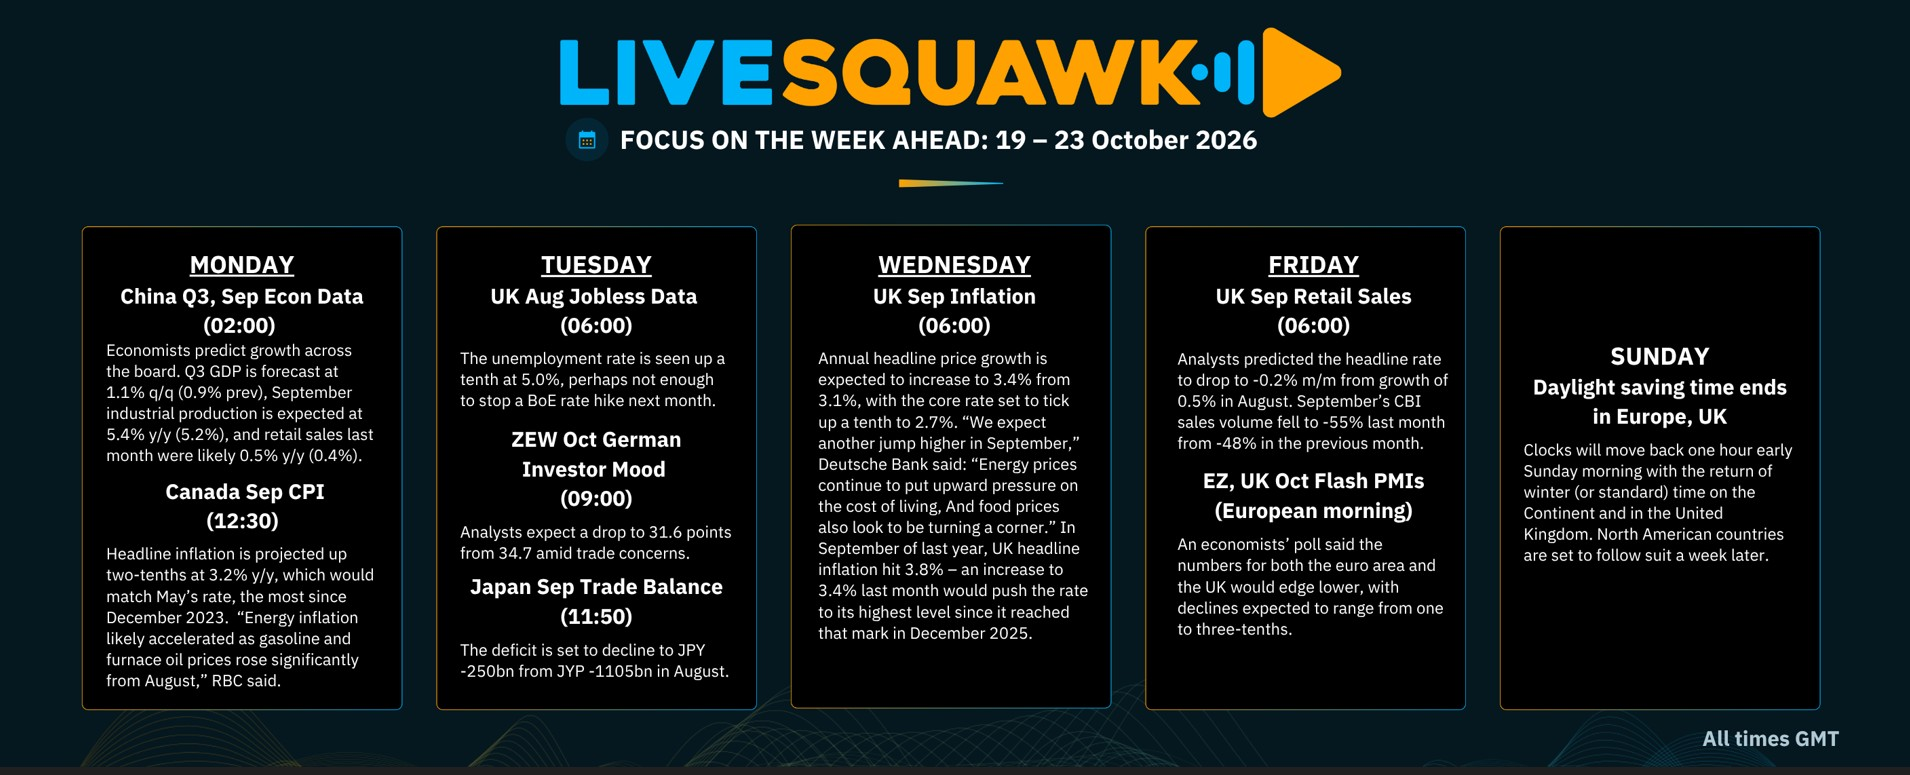
- ▸Eurozone Flash PMIs (week ahead): Manufacturing and services expected to remain in expansion but cool slightly; Germany's services PMI seen hitting an eight-month high even as ZEW sentiment slips after five consecutive gains.
- ▸UK CPI (week ahead): Consensus at 3.4% YoY (nine-month high), core at 2.7%; Rightmove data already shows mortgage affordability tightening (2Y fixed rate up to 5.55% from 5.29%), reinforcing the case for sustained BoE restrictiveness.
- ▸UK Labour Market (week ahead): Unemployment seen rising to 5.0%; wage growth expected at its weakest since 2020 — a key input for the BoE's inflation-persistence assessment.
- ▸US Flash PMIs (week ahead): Expected to show mild slowdown but resilient growth; final Michigan sentiment and housing data (permits steady ~1.40M, starts up to ~1.30M) also due.
- ▸Canada CPI (week ahead): Consensus +0.2% m/m rebound; core steady at 2.6%.
- ▸US Fed communications blackout: In effect from October 17 through October 29 (FOMC on October 28).
Asian Overview
- ▸Australia: RBA Assistant Governor Kent acknowledged the labour market is loosening faster than the Bank forecast, raising the hurdle for an immediate follow-up hike at the November 3 meeting.
- ▸New Zealand: The September goods trade deficit widened to NZD 1.97B (imports NZD 8.44B, exports NZD 6.47B), with annual imports rising 18% vs. exports +12% — the deterioration primarily driven by higher petroleum import costs rather than export weakness.
- ▸China: Q3 GDP expanded 4.5% YoY (consensus 4.4%, Q2: 4.3%) and 1.2% QoQ (consensus 1.0%), though cumulative 9M growth of 4.6% merely matched expectations. September activity data was firm: retail sales accelerated to 1.1% YoY (strongest since June), industrial production rose 5.5% (six-month high), and the surveyed unemployment rate fell to 5.2%. The principal weakness remains investment.
Focus Events, Mon 19th
EU Session:
- ▸06:50 — ECB Elderson (No Known Bias).
US Session:
- ▸13:00 — CAN: BBG Nanos Conf.
- ▸13:30 — CAN: CPI, Core CPI.
- ▸15:00 — US: NAHB Housing Market Index.
- ▸15:30 — CAN: BoC Biz Outlook.
Bond Supply Events: N/A.
News From the Trenches
- ▸China's Q3 GDP growth accelerates to 4.5%, beating estimates.
- ▸BoJ Governor Ueda says underlying inflation is quite close to the 2% target.
- ▸IMF says the BoJ may need to tighten faster if inflation exceeds forecasts.
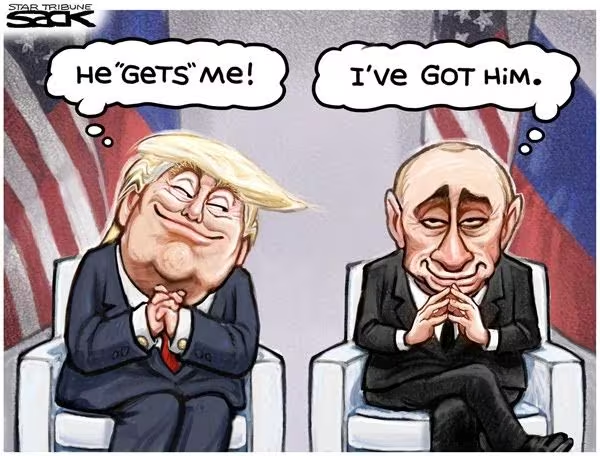
- ▸Putin floats a summit with Trump and Xi to decide Ukraine's fate.
- ▸Zelenskyy says Trump is pushing Ukraine to capitulate to Russia.
- ▸Rubio says Trump may take up to 60 days to decide on Russian sanctions.
- ▸Oil tumbles as Trump's Russian sanctions waiver raises supply prospects.
- ▸France faces the aftermath of its worst unrest in years as Macron urges calm.
- ▸ECB's Lagarde says the bond sell-off will slow inflation.
- ▸Euro weakens as French protests and Russia risks weigh on sentiment.
- ▸US futures rise ahead of a busy earnings week.
Sources: Earnings Whispers — Earnings Expectations, Calendar & Analysis · WSJ — Putin Floats a Summit With Trump and Xi to Discuss Ukraine Deal · CNBC — China's economic growth quickens as exports surge, stimulus rolls out · Bloomberg — Trump Pressed Ukraine to Capitulate to Russia, Zelenskyy Says · Bloomberg — Lagarde Sends Message to Putin at IMF That War Harms Prosperity · WSJ — French Leaders Trade Blame After Rioting Sweeps the Nation · Reuters — ECB's Lagarde says bond selloff will slow inflation · Reuters — Dollar firmer, euro weakens as French protests turn violent · Reuters — Oil tumbles as Trump's Russia sanctions waiver may lead to more fuel supplies · Bloomberg — Stock market today: Dow, S&P live updates
The French Fiasco Continues
The Upcoming Budget Vote & Political Stalemate
The National Assembly opened debate on the revenue portion of the budget amidst chaotic political fracturing.
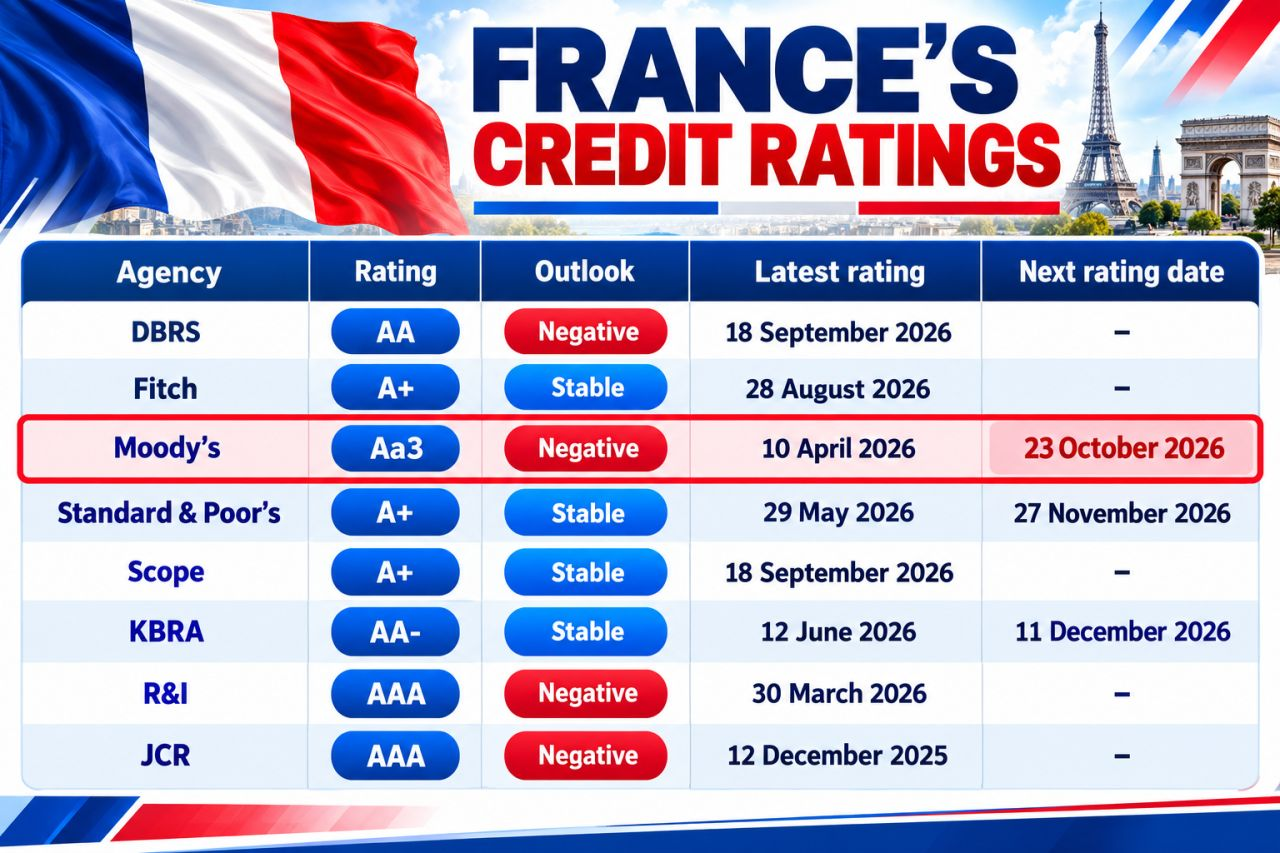
- ▸The Make-or-Break Vote: The first critical vote on the 2027 budget is scheduled for Tuesday (20 October).
- ▸The Risk of Collapse: Because the July 2024 snap elections left the parliament divided into three adversarial, uncooperative blocs (the far-right National Rally, the left-wing New Popular Front, and Lecornu’s center-right group), the government lacks a stable majority. If the opposition unites to defeat the budget or tables a successful no-confidence motion, the government could collapse.
Monday's Papers
- ▸The Times: The tough economic backdrop to John Healey’s first budget will be laid bare this week with new data set to show rising inflation, tens of billions of pounds of government borrowing and historic levels of youth joblessness.
- ▸The Guardian: British steelmakers have been pushed further behind European rivals on electricity costs after the US-Israeli war on Iran caused a surge in global gas prices.
- ▸The Times: President Macron has blamed an ‘unprecedented’ wave of violence in France on ‘ultra-left’ rebels seeking to overthrow the state as well as criminals engaged in looting.
- ▸Financial Times: Cracks are appearing in America’s debt-laden $10tn AI infrastructure boom amid project delays and a public backlash; at least 47 large datacentre projects have been delayed this year, according to RegLayer, a regulatory intelligence company.
- ▸Daily Mail: Banks are set to post bumper results as John Healey eyes a £7bn windfall tax raid on their profits in a bid to repair the public finances.
- ▸The Guardian: Profits at Condé Nast’s UK arm slumped by more than a third last year, according to figures published shortly after the billionaire family that owns the luxury magazine group and titles from Vogue to GQ ruled out a sale.
- ▸Financial Times: The City of London Corporation is considering tax rises and cuts to services as the governing body for the Square Mile tackles an expected £70m budget shortfall.
- ▸The Guardian: The development of a huge AI datacentre at Loughton in Essex hailed by the UK government has received a fresh setback after Microsoft pulled out of the project over concerns about power supplies.
- ▸The Daily Telegraph: Britain could bend its fiscal rules in the future to keep funding net zero projects amid looming Whitehall spending cuts, the Energy Secretary has suggested.
- ▸The Daily Telegraph: Toyota has warned it could scale back sales in Britain because of ‘unrealistic’ electric car targets.