Macro PolicyMarket WatchLIVE WIRELatestOctober 27, 2026
ZENITHWAVE CAPITAL 27TH OCTOBER MISSIVE
MacroMarkets
HF
The Hedge Front / ISFT
Global Macro Bureau
Subscribe for the weekly briefing. Unsubscribe at any time.
Fast-moving regulatory developments, central bank communications, and systemic market infrastructure intelligence.
Showing 8 of 27 dispatches
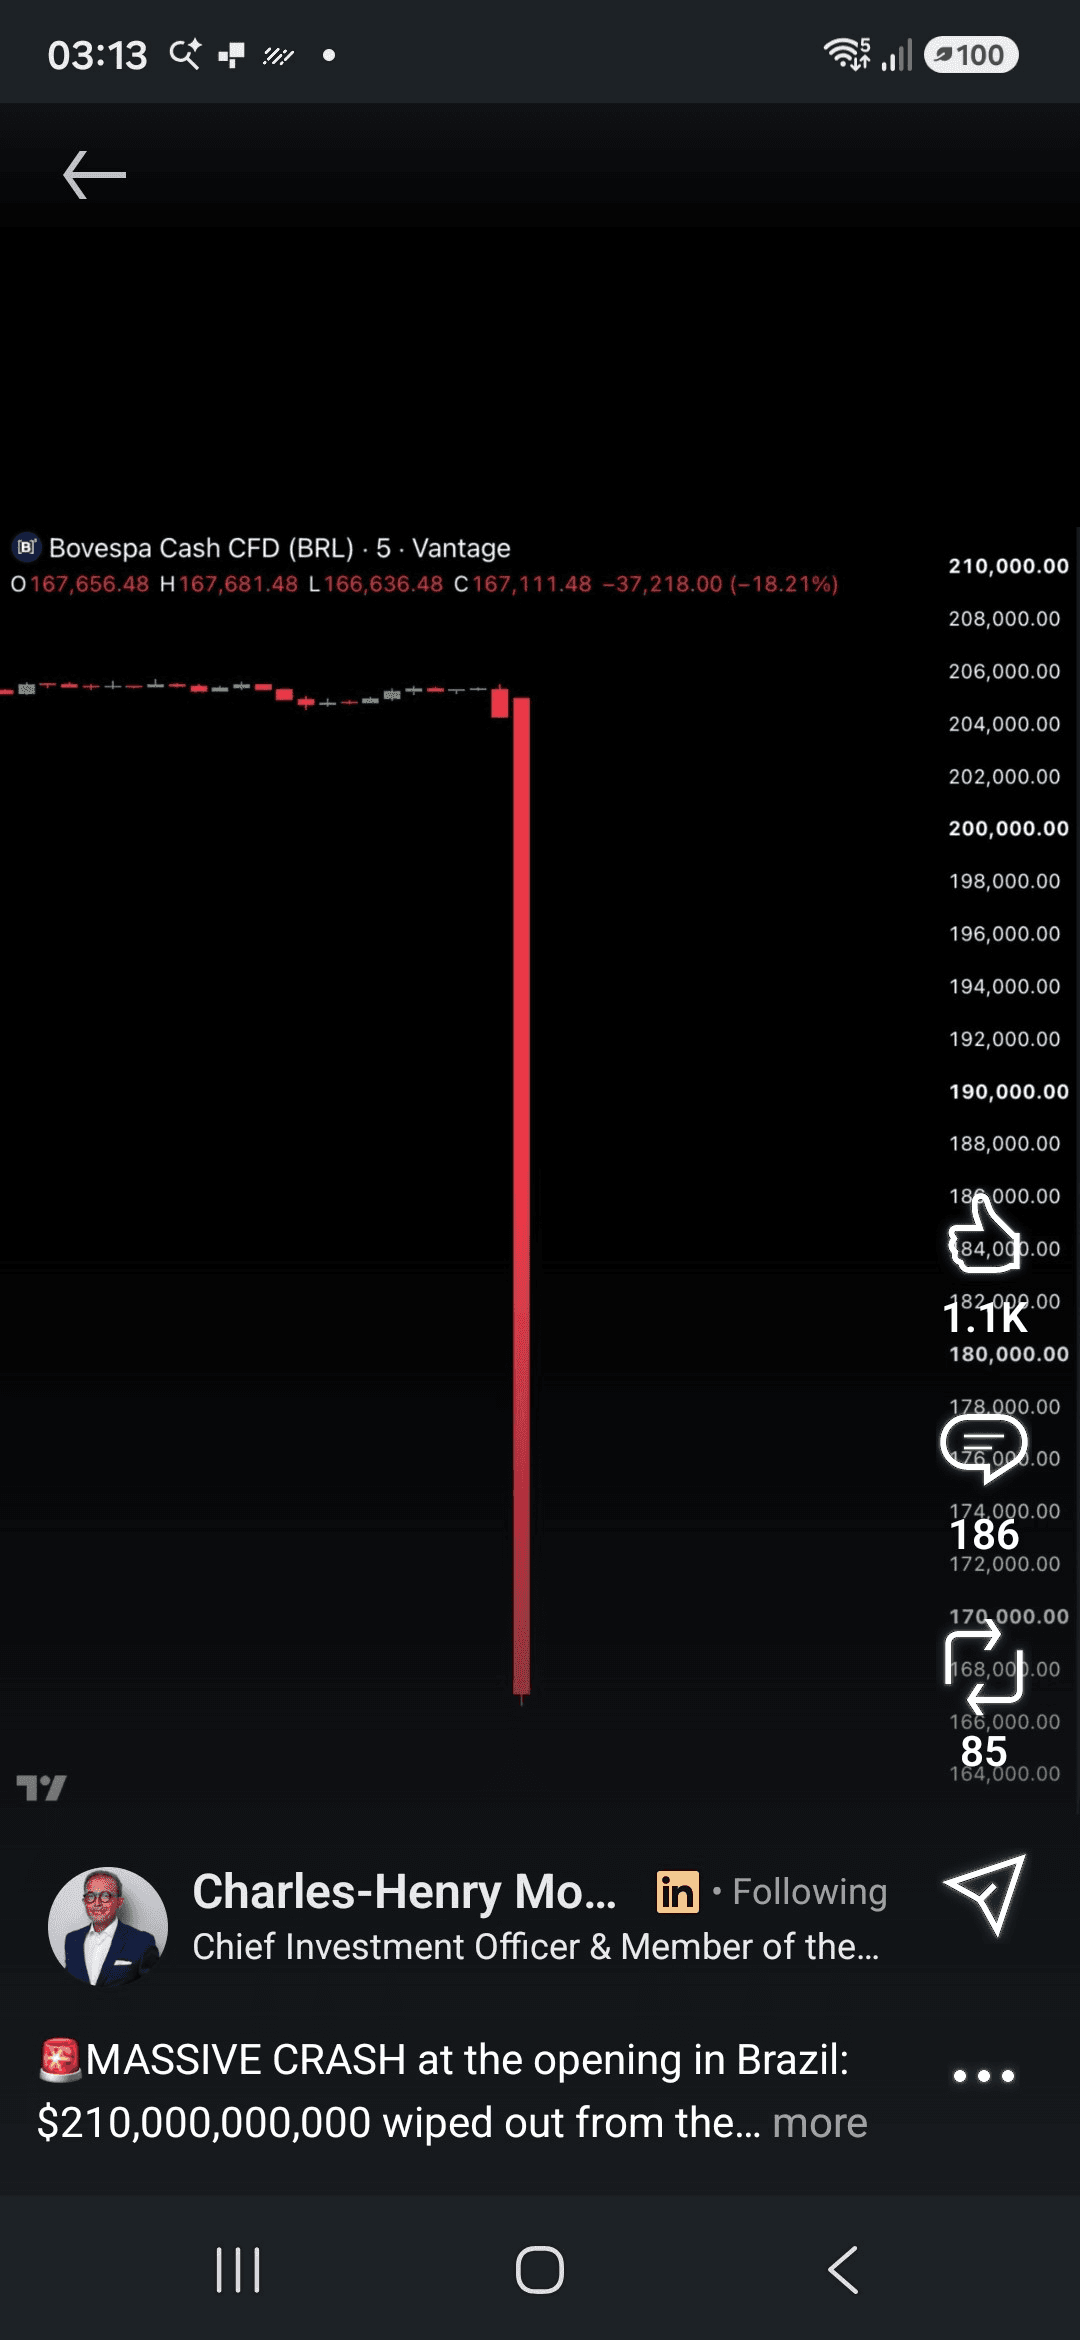
MORNING ; LEFT WING WIN BRAZIL ELECTION AND STOCK MARKETS HAS ITS BIGGEST DUMP IN 36 YEARS ! WHO SAYS NEWS NOT IMPORTANT ? THIS WEEK REALLY STARTS ON WEDNESDAY MONDAY WE SAW AI RISK APPETITE BOUNCE ,WHILE OIL REMAINS THE BIGGEST THREAT TO…
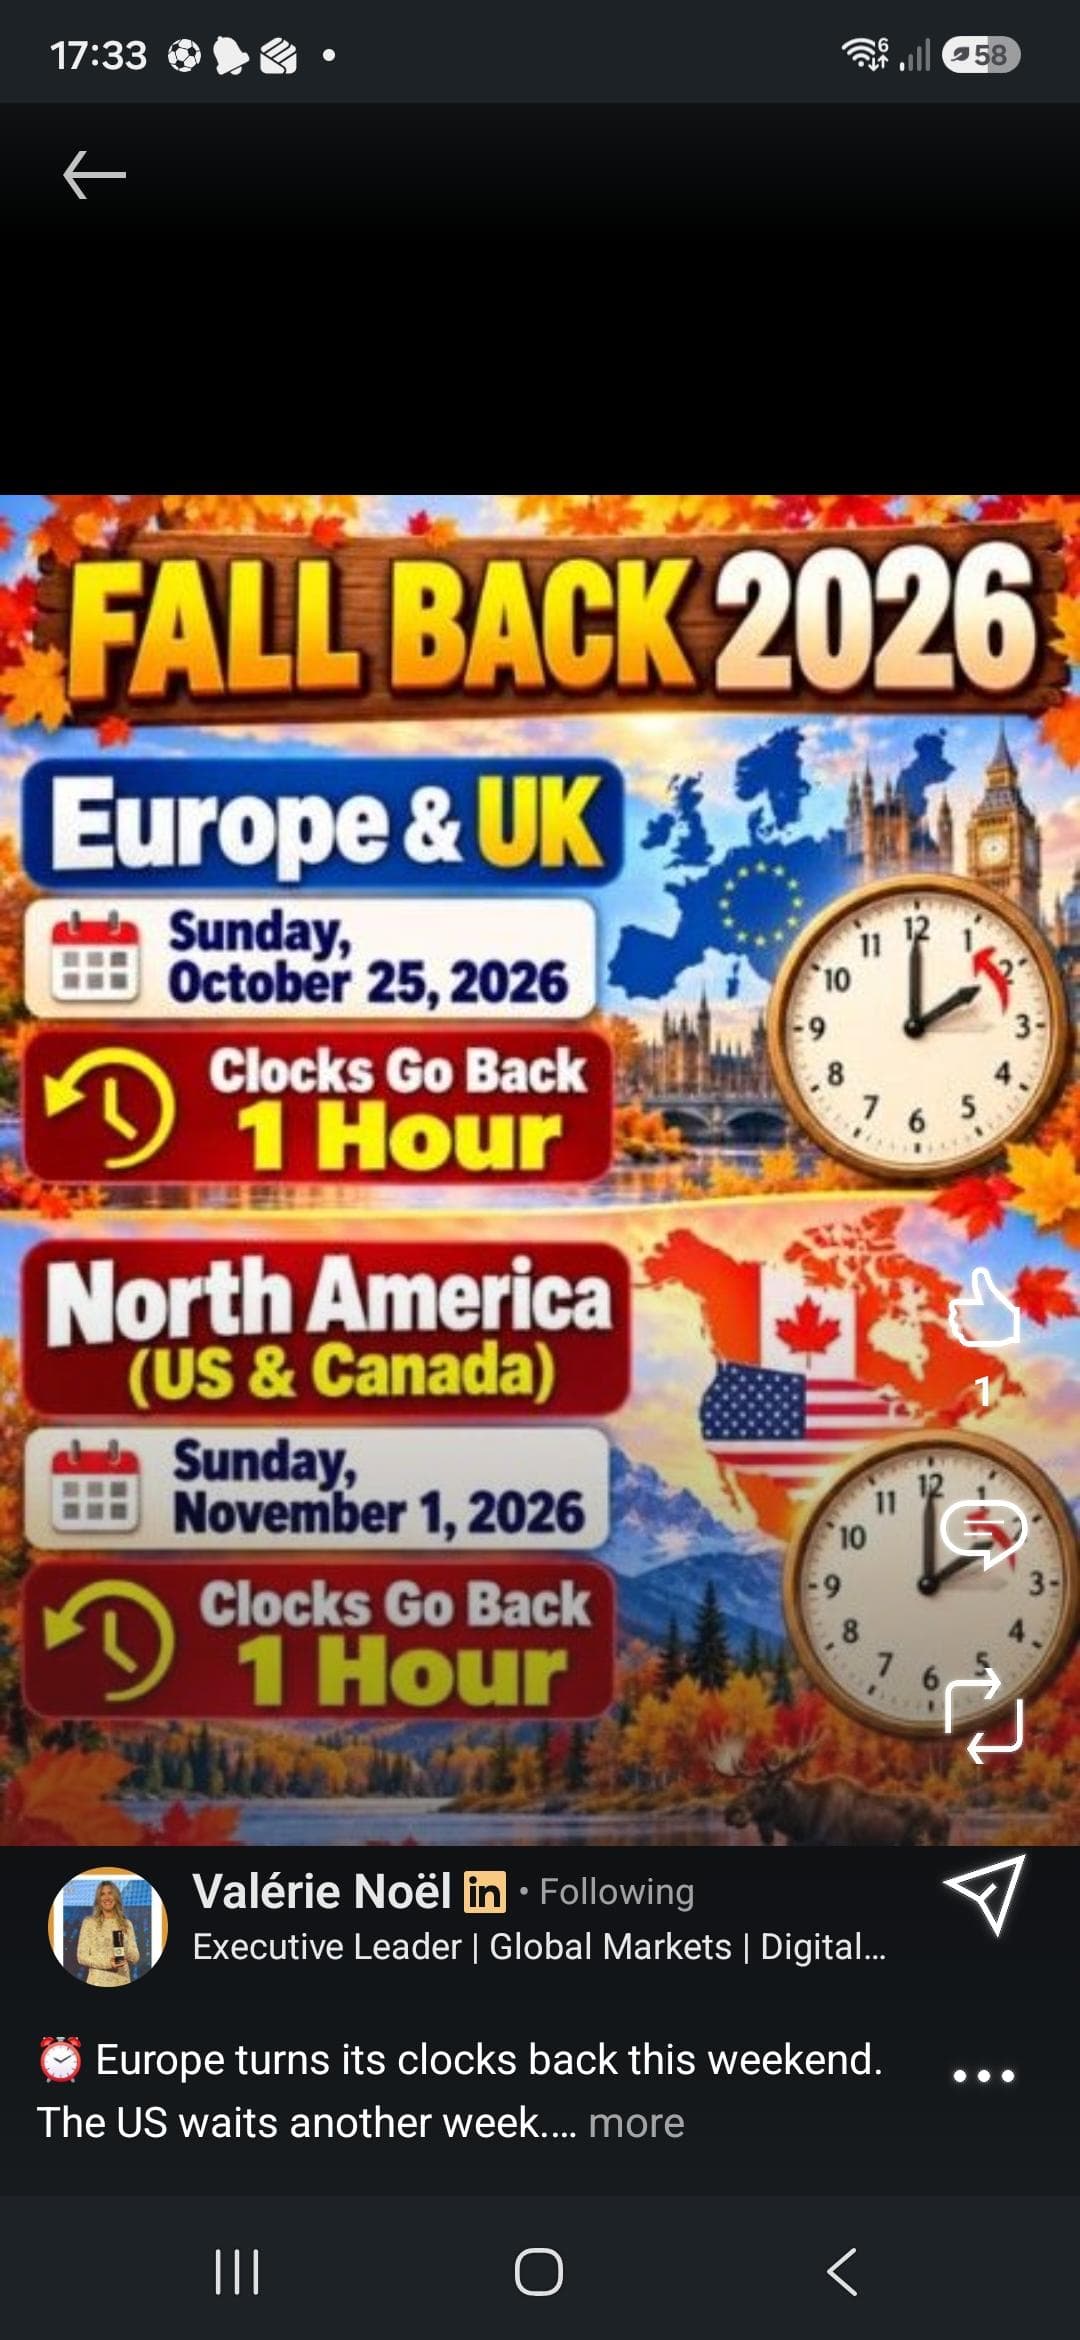
Clocks go back in Europe and the UK as we enter a huge week: the UK Budget, RBNZ, Bank of Canada, FOMC, ECB and BOJ decisions, plus Q3 GDP and US PCE.
A massive Thursday saw bond yields post their biggest drop in over a year, the SOX slide 6% and Meta fall nearly 8% as Brent zoomed to $113. We preview flash PMIs, UK retail sales and Michigan sentiment.
Wednesday’s rally proves short-lived as the Nasdaq and Nikkei slide on reports of US embassy departures in the Middle East. Jobless claims, ECB speakers and a busy Asian central-bank slate headline Thursday.
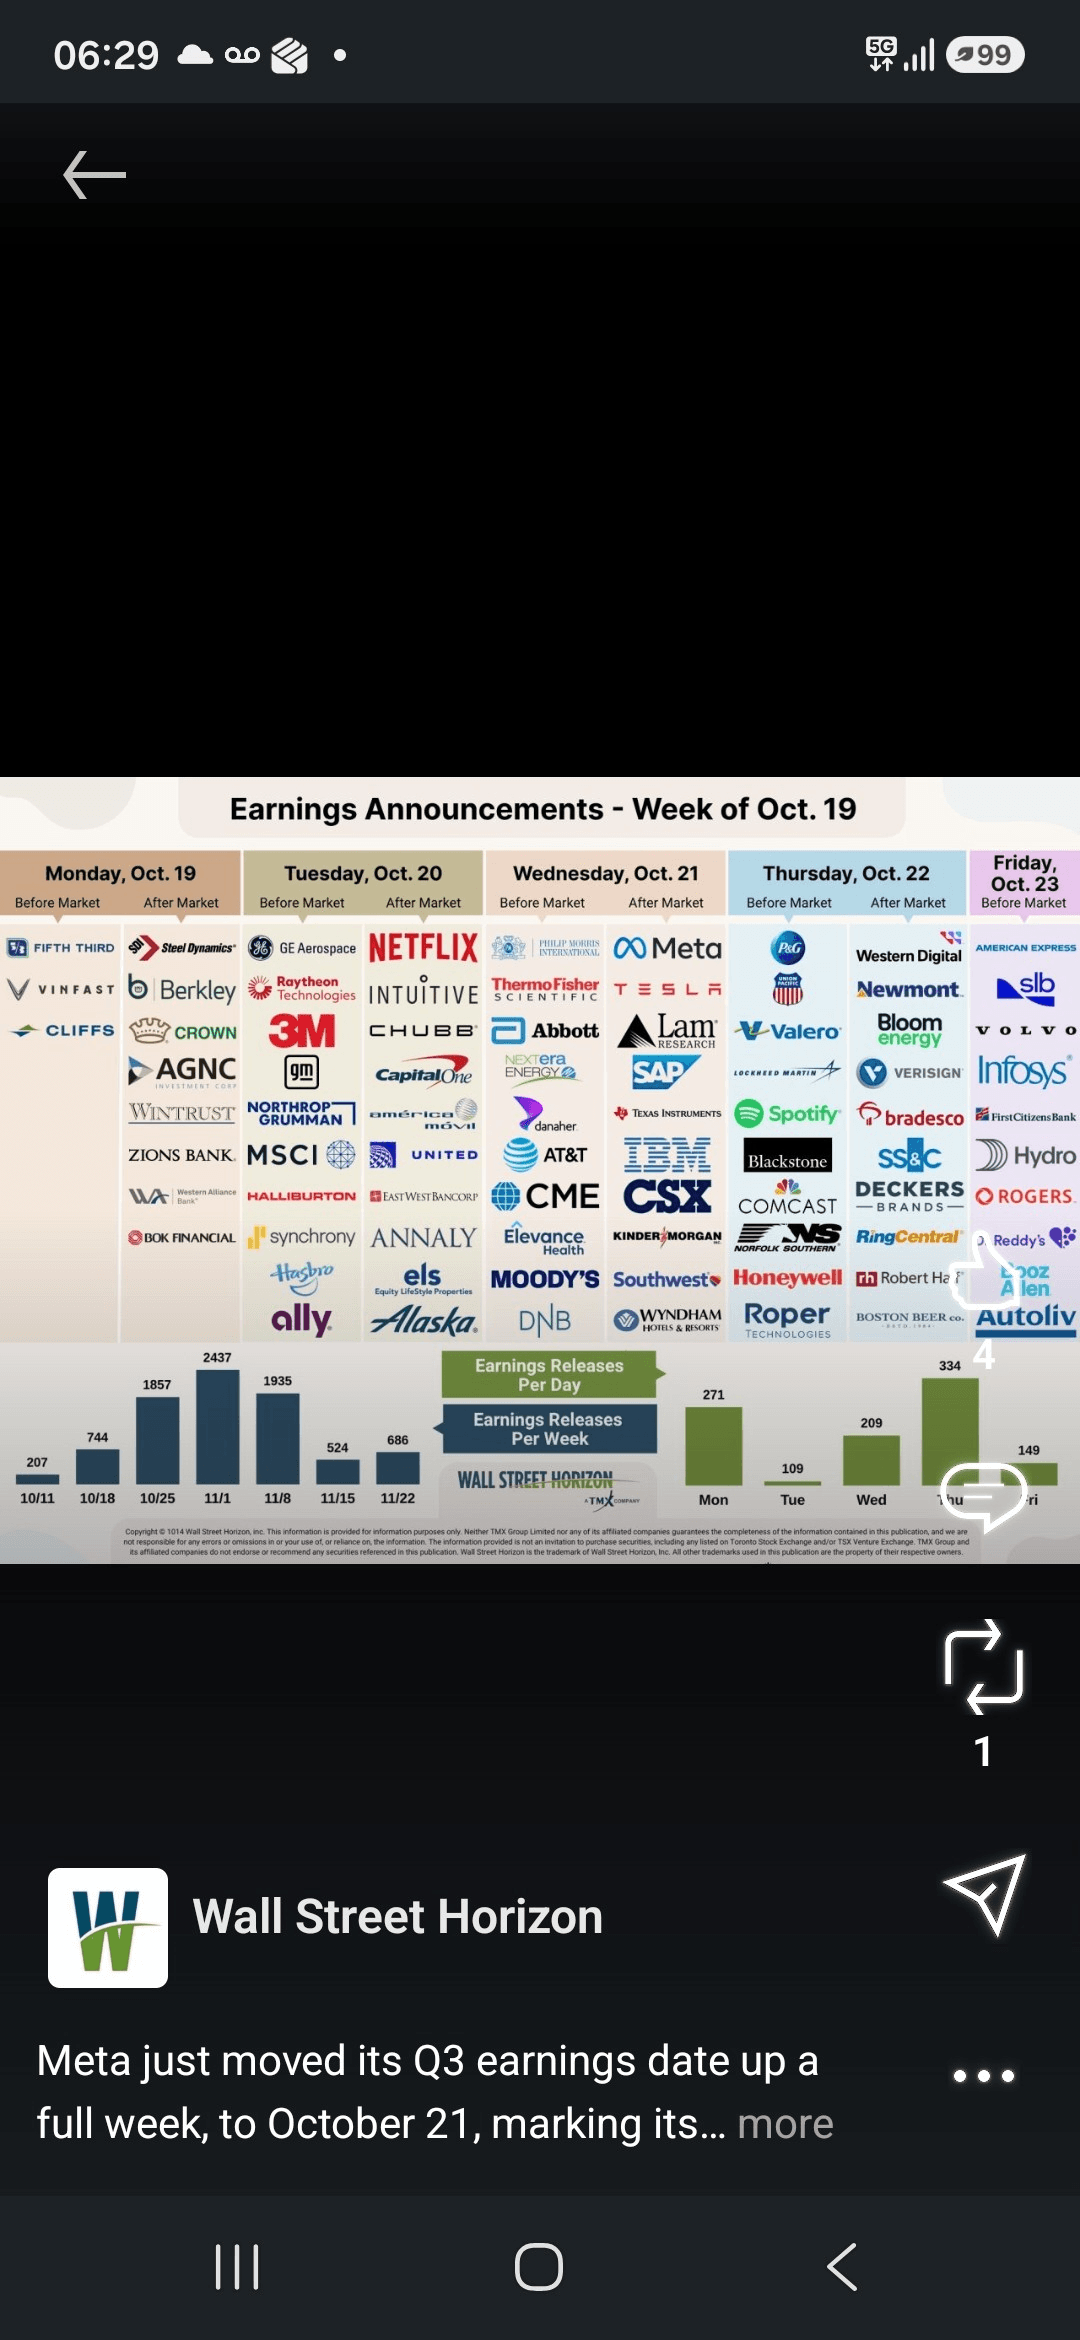
Markets groaned on bad news from France before bouncing at the Wall Street bell. Chipmakers drag the Nasdaq 100, oil whipsaws on Iran headlines, and UK CPI, Bailey and Lagarde headline Wednesday.
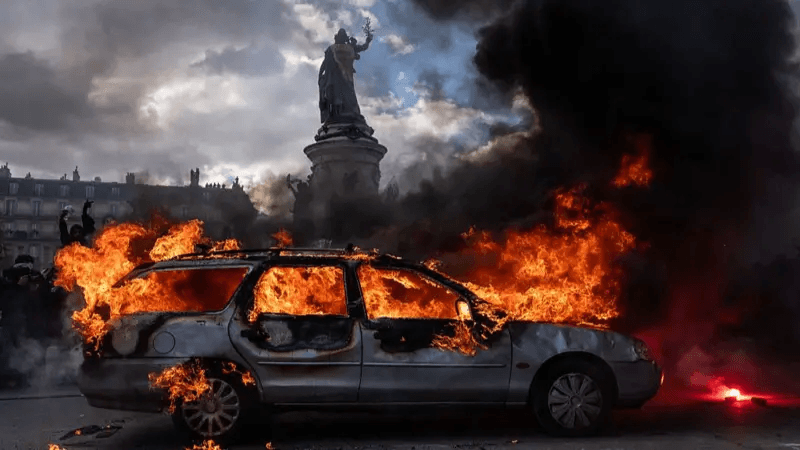
France burns ahead of a huge budget vote as OATs sell off and widen versus Bunds. Treasury yields climb towards 5.15%, oil hits a five-month high on Hormuz threats, and the euro slides towards $1.12.
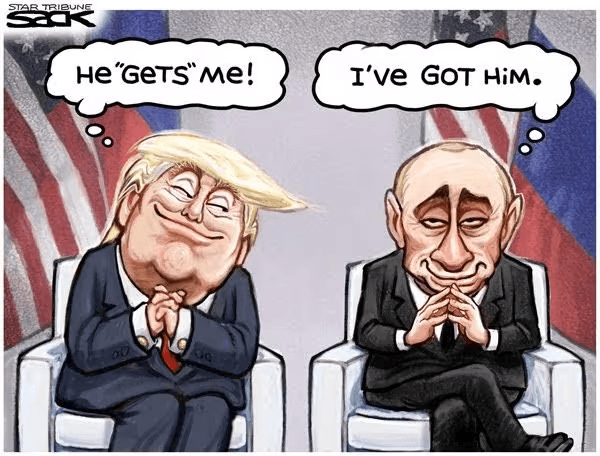
France’s worst unrest in years puts Europe’s debt question front and centre, while US indices bounce on renewed peace hopes. We preview flash PMIs, UK CPI and Tuesday’s critical French budget vote.
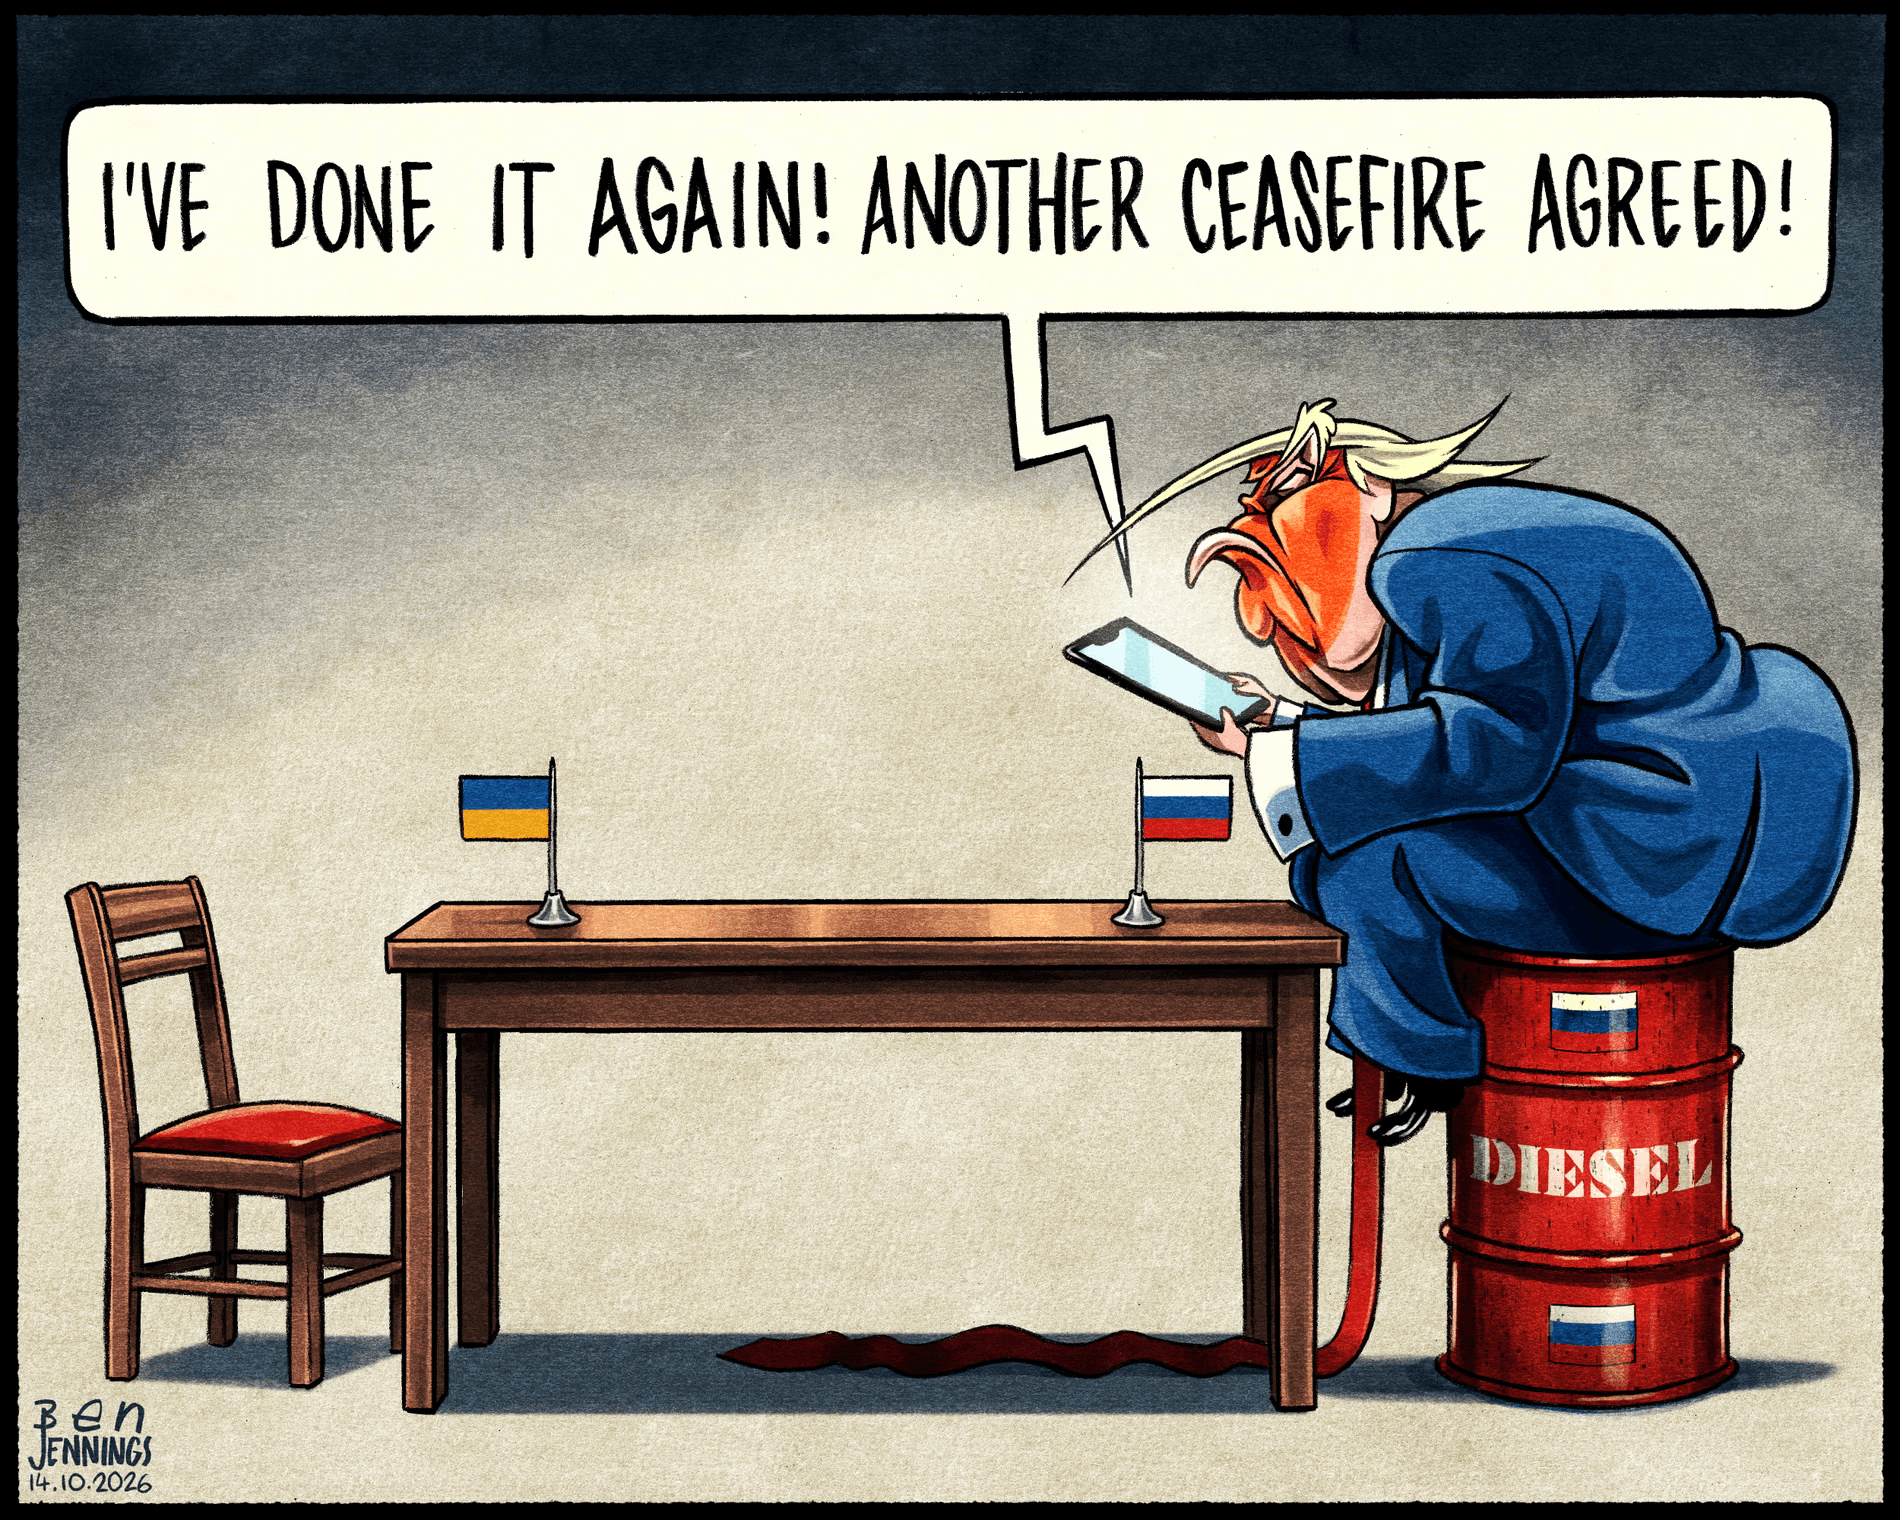
A fast reversal in indices after OPEX capped a week of sticky inflation, rising geopolitical skirmishes and mounting debt concerns. We stay bearish, warn about leverage, and preview next week’s inflation data and flash PMIs.